BRICS Summit Produces Neither Common Currency nor Operational Payment System
 Antonio GraceffoUpdated 2 hours Ago4 Mins read
Commentary
For more than 10 years, the BRICS countries have threatened to de-dollarize. Currency and payment settlement have appeared on the agenda of nearly every BRICS summit.
Each time, pundits and analysts publish doomsday scenarios about what would happen to the U.S. economy if the dollar lost its status as the world’s reserve currency.
It began ahead of the 2013 Durban summit, when officials discussed the feasibility of a common currency alongside plans for the New Development Bank. The summit produced the bank, but not the currency.
However, the New Development Bank finances development projects; it is not a central bank capable of issuing and managing a common currency. Its first loans were denominated entirely in dollars, and it did not approve its first non-dollar loans until 2019.
The dollar remains dominant today. Local-currency lending, driven mainly by yuan (or renminbi)-denominated loans, accounts for only about 22 to 25 percent of the bank’s portfolio, while other member currencies trail far behind.
Yet every proposed alternative has failed to materialize, whether a common currency, a common cryptocurrency, or the adoption of the yuan by all BRICS countries. Each option faces structural problems that BRICS has so far failed to resolve.
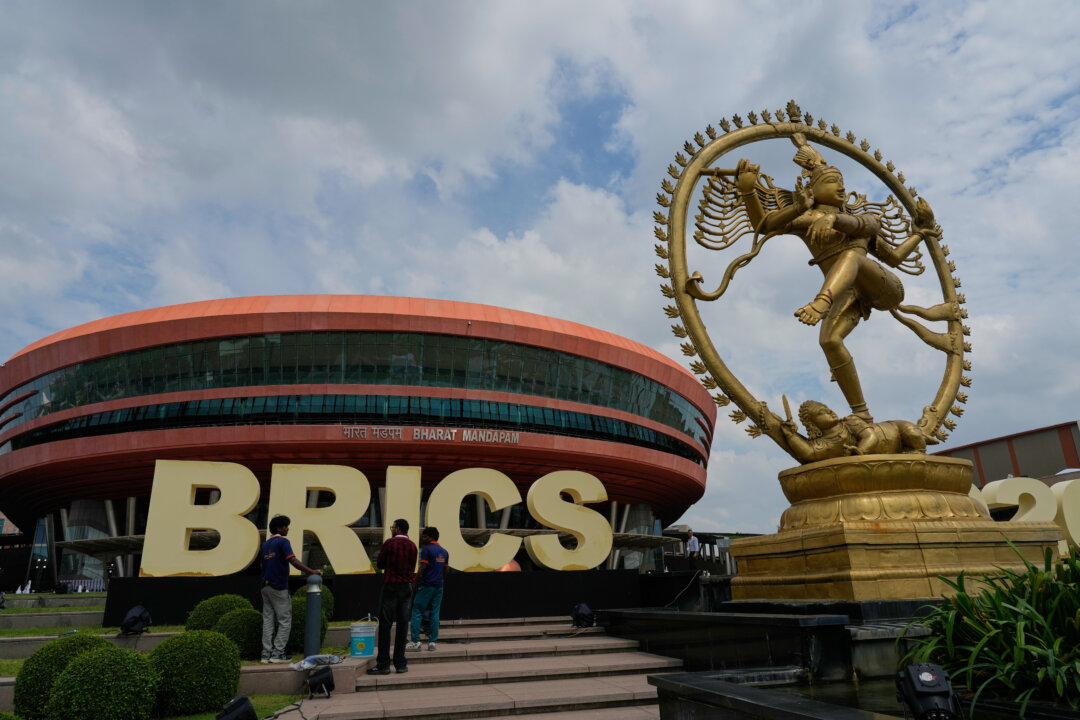
The 18th BRICS Summit, held in New Delhi from Sept. 12 to 13, was no different. It produced neither a common currency nor a proposal to create one.
The New Delhi Declaration, a 140-point document unanimously adopted on the summit’s first day, addresses payment systems in three passages but offers no framework for a common currency. It states that the BRICS Payment Task Force is exploring more efficient cross-border payment mechanisms, building on the 2024 Kazan and 2025 Rio declarations, and refers to discussions about settling trade in local currencies.
This continues the distinction India drew ahead of the 2023 Johannesburg summit, when then-Foreign Secretary Vinay Mohan Kwatra said that increasing trade in national currencies was the immediate goal, not the creation of a common BRICS currency.
Although not explicitly mentioned in the declaration, BRICS Pay is intended to link national payment and financial messaging systems, including India’s Unified Payments Interface (UPI), China’s Cross-Border Interbank Payment System (CIPS), Brazil’s Pix, and Russia’s System for Transfer of Financial Messages (SPFS).
The proposed decentralized network would facilitate real-time cross-border payments in local currencies without using dollars or routing transactions through the Society for Worldwide Interbank Financial Telecommunication (SWIFT). It is not a common currency or a euro-style monetary union.
Ahead of every BRICS summit, alternative-media outlets proclaim the demise of the dollar and describe BRICS Pay as though it were already operational. Mainstream and pro-Beijing media speculate about how it could affect trade within the bloc and challenge the dollar if implemented. However, BRICS Pay is not operational. It remains a proposal and development project.
At the BRICS Business Forum in Moscow, held shortly before the 2024 Kazan summit, participants received test cards loaded with 500 rubles as part of a controlled demonstration of decentralized messaging and QR-code payments.
The demonstration established that a Russian-funded test card loaded with Russian rubles could successfully purchase $5.20 worth of goods at selected locations in Russia under controlled conditions. That is a far cry from challenging the dollar, which accounts for 89 percent of the world’s $9.6 trillion in daily foreign-exchange trading.
Nor did the test attempt to solve BRICS Pay’s central problem: linking the incompatible payment and banking systems of its member countries.

(From L to R) Chinese leader Xi Jinping, Brazilian President Luiz Inácio Lula da Silva, South African President Cyril Ramaphosa, Indian Prime Minister Narendra Modi, and Russian Foreign Minister Sergei Lavrov gesture as they attend the 2023 BRICS Summit at the Sandton Convention Center in Johannesburg on Aug. 24, 2023. Gianluigi Guercia/AFP via Getty Images
Internal divisions continue to obstruct the project. Russia and Iran favor rapidly developing alternatives that bypass SWIFT, while India rejects replacing the dollar or creating a monetary union. India instead favors linking national central bank digital currencies and existing fast-payment systems.
Brazil is the only member whose head of state has repeatedly raised the idea of an actual common currency. In 2023, Brazilian President Luiz Inácio Lula da Silva proposed a common currency with Argentina. However, Argentina is not a BRICS member, and the incoming Milei government rejected its BRICS invitation shortly before the bloc’s 2024 expansion took effect.
That same year, Lula raised the idea within BRICS, asking during Dilma Rousseff’s inauguration as president of the New Development Bank why international trade had to be conducted in dollars. Yet Lula later denied that an active proposal existed, telling the media in February 2026 that there was no plan to create a new BRICS currency. No other member government has endorsed the idea.
The digital-currency alternative favored by India is not a shared capability. Although all 10 BRICS members are exploring central bank digital currencies, nine have reached the pilot stage, while Egypt and Ethiopia remain in the research stage. None has fully launched a CBDC, and the separate national pilots do not form an interoperable BRICS network. Each was developed under its own technical standards, laws, exchange controls, and regulatory system.
Digitizing a currency does not, by itself, resolve the settlement problems associated with physical currencies. A joint report by the Bank for International Settlements, the International Monetary Fund, and the World Bank found that interoperability between CBDC systems must be deliberately engineered. It identified the lack of international agreement on technical standards and governance as a major barrier to CBDC-enabled cross-border payments.
A Bundesbank analysis reached the same conclusion. Differences in national laws, data-handling rules, and cybersecurity requirements can prevent systems from being linked, while central banks remain reluctant to surrender autonomy to joint governing institutions.
A CBDC remains a liability of its issuing central bank, subject to that country’s legal framework, exchange controls, and compliance regime. Linking CBDCs across borders, therefore, faces the same sovereignty and regulatory obstacles that already complicate settlement in physical local currencies.
What this all means for the United States is that the dollar will remain king for the foreseeable future. Nevertheless, pro-Beijing voices will likely emerge before the next BRICS summit, once again chanting that the dollar is dead.
Views expressed in this article are opinions of the author and do not necessarily reflect the views of The Epoch Times.
Airbnb Commits $250 Million to Help Finance Housing Projects
The Airbnb app on a smartphone in this photo illustration taken on...
US 10-year Yield Hits 5 Percent, Highest Since 2023
The benchmark Treasury yield rose above 5 percent on Monday as investors...
China’s Growing Auto Presence Forces Europe to Rethink Its Car Industry
As Chinese automakers gain ground in Europe, the continent’s car industry is...
Canada’s Health-Care Illusion
CommentaryCanada does not have to choose between universal health care and health-care...