Beijing Reforms Home Finance Rules
 Milton EzratiUpdated 1 day Ago2 Mins read
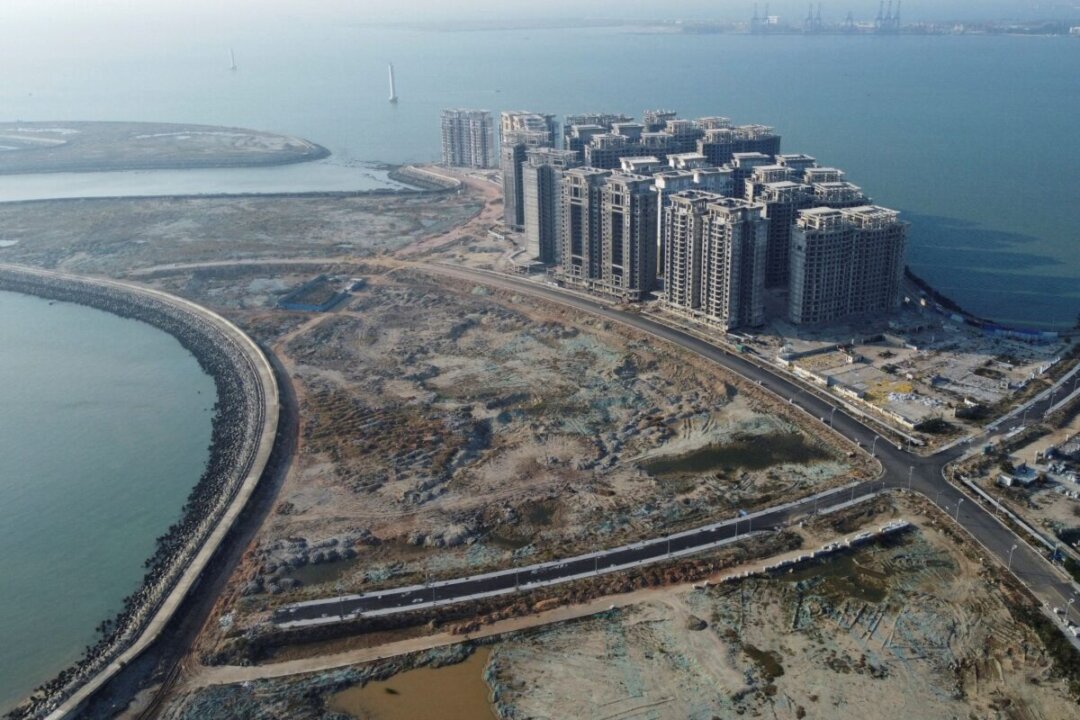

An aerial view shows the 39 buildings developed by China Evergrande Group that authorities have issued demolition orders for in Hainan Province, China, on Jan. 6, 2022. Aly Song/Reuters
Commentary
Beijing has issued new rules on homebuying. It will now allow longer mortgage terms than previously, which should relieve the monthly cost of financing a property. It has also moved to protect buyers from the dangerous practice of pre-buying homes before they are complete.
The details of these reforms are straightforward enough. One lengthens the permissible term of a mortgage from 30 to 40 years. Though the new arrangement will increase the cumulative amount of interest paid over the life of a mortgage and keep homes tied to a mortgage for longer, it will nonetheless reduce the monthly payment on that mortgage.
The second change insists that an apartment be certified safe and ready to receive occupants before mortgage arrangements can be finalized. Previously, buyers could pay for an apartment and arrange for a mortgage on it before it was complete.
This second reform may seem obvious to Western readers. Who would take on a mortgage on a house or apartment that is not yet complete? Still more bewildering, what lender would lend money secured by a property that does not yet exist?
But until now, or at least at the onset of the property crisis, this kind of pre-buying and pre-financing was common in China. When the housing crisis broke, this practice compounded and extended its effects, forcing millions of Chinese who had engaged in this pre-buying to pay on a mortgage tied to an apartment that was not yet complete and might never be completed.
That state of affairs exacerbated the economic effects of the crisis, and when these borrowers refused to pay on their mortgages, the financial ramifications became even more difficult to manage.
These reforms certainly would have done more good if they had been put in place before the crisis, but they are nonetheless useful now. The one will give Chinese homebuyers more financial options than previously. The second will protect homebuyers from the clear risks—to individuals and the economy—of pre-buying.
The second reform will also guard against complications should China face another such crisis. But neither will help China much in moving past the severe repercussions it still suffers from the disaster that befell it in 2021.
To be sure, the ability to arrange a longer maturity mortgage may help stimulate homebuying, but only marginally. Homebuying in China has fallen in every month but eight during the past five years. That is a trend that will take more than minor relief on monthly payments to reverse.
What is more significant is that residential real estate values in China have fallen cumulatively by some 25 percent, with no significant break since the crisis began five years ago. Not only has that loss eroded household net worth and, in turn, discouraged spending, but it has also stifled the very idea of homeownership. Prospective homebuyers reasonably question whether there is any sense in borrowing to buy a depreciating asset.
Though these measures offer little to address China’s economic problems, they are nonetheless welcome. For one, they do offer future protections against the practices that caused so much pain among the homebuying public during the property crisis and exacerbated its ill effects. For another, there is an indicator, albeit a small one, that the authorities in Beijing are less out of touch with China’s economic needs than it sometimes seems.
However, it is doubtful that either measure will do much to lift China’s economy from the ill effects of the property crisis that began in 2021 and persists to this day. Indeed, it looks as though even Beijing knows that these measures cannot answer this larger problem.
Views expressed in this article are opinions of the author and do not necessarily reflect the views of The Epoch Times.
USA: 250 Years as a Beacon of Liberty and Refuge from Tyranny
AdvertorialSince its founding 250 years ago, the United States of America has...
iPhone Owners Can Submit Claims in Apple’s $250 Million Settlement
Millions of iPhone customers can now submit claims of up to $95...
ABC’s Four Corners Program Found in Breach of Standards Over Use of Anonymous Sources
The Australian Broadcasting Corporation (ABC) logo is seen in the press gallery...
Kalshi Seeks Approval to Allow Some Users to Borrow Funds to Place Bets
Kalshi, the popular prediction market platform, is seeking federal approval to allow...