More US Homebuyers Apply for Riskier Mortgages as Interest Rates Top 7 Percent
 Andrew MoranUpdated 3 hours Ago3 Mins read
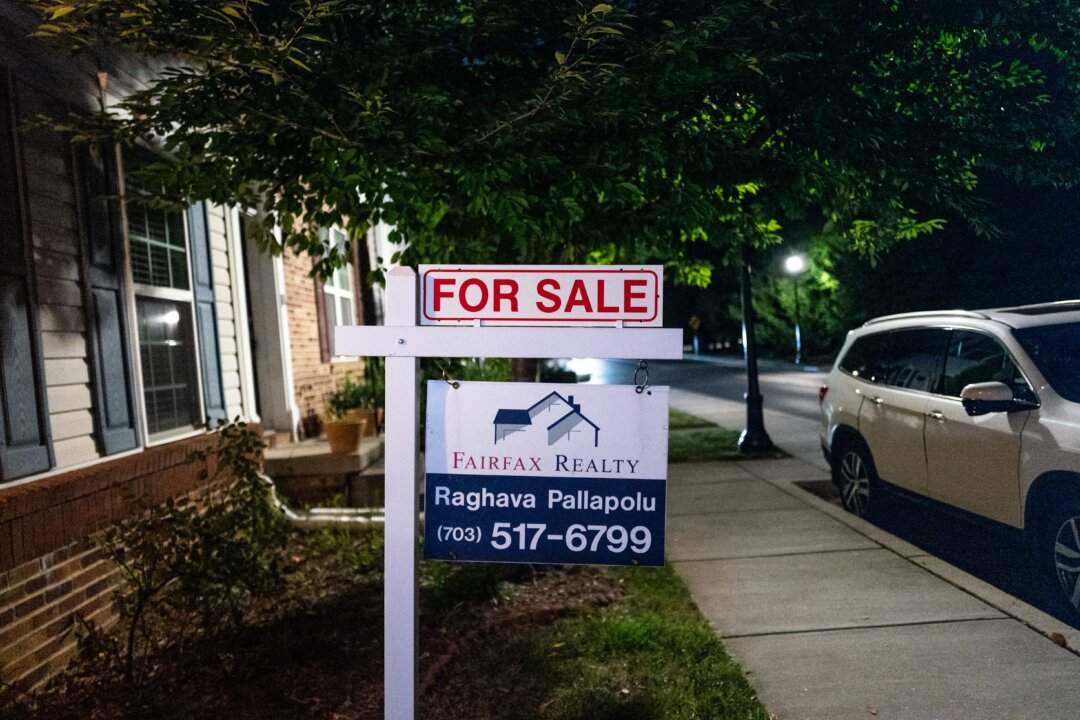
Higher interest rates pushed prospective homebuyers toward riskier mortgages last week, new industry data show.
The total volume of mortgage applications declined almost 2 percent for the week ending Sept. 18, according to a report released by the Mortgage Bankers Association on Sept. 23. This represented the third consecutive weekly drop.
Applications for a mortgage to purchase a home fell 1 percent and were down 11 percent from the same time a year ago. Refinancing applications also fell to their lowest levels since February 2025, down 3 percent monthly, and were 62 percent lower year over year.
“Applications for both refinance and purchase loans declined further last week, noting that the comparison is to the week that included the Labor Day holiday,” Mike Fratantoni, the group’s senior vice president and chief economist, said in a news release.
Last week’s decline aligned with the sharp increase in interest rates.
Because fixed-rate mortgage costs have accelerated in recent weeks, borrowers sought riskier adjustable-rate mortgages—also known as ARMs—Fratantoni added.
“With fixed rates much higher, more borrowers opted for ARMs, with the ARM share reaching 9.8%, as rates for 5/1 ARMs were more than a percentage point lower than those for fixed rate loans,” he said in a statement.
The average contract interest rate for 30-year fixed-rate mortgages rose to 7.12 percent, from 6.97 percent—the highest since May 2024.
Mortgage rates have increased by more than 100 basis points since the United States and Israel launched a joint military operation against Iran in late February. The conflict, approaching the seven-month mark, has sent Treasury bond yields surging.
The benchmark 10-year Treasury yield reached 5 percent again midweek, up from 3.96 percent before the war in Iran began. The mortgage market generally tracks government bond yields, resulting in higher borrowing costs for prospective buyers.
ARMs start with a lower fixed rate for three to ten years, then change every six months or annually based on market conditions. This product saves borrowers money upfront but can swing higher or lower based on benchmark rates.
Mortgage rates have ticked up slightly so far this week.
As of Sept. 22, the average 30-year fixed rate was 7.17 percent, according to Mortgage News Daily.
Fueling Interest Rates
Global energy markets and inflation data have been the driving forces behind interest rates and will determine the Federal Reserve’s next policy decision, says Jeff DerGurahian, head economist at loanDepot.
“For now, rates appear to be standing at a fork in the road. Softer inflation and lower oil prices could provide relief, while continued energy pressure could keep mortgage rates near or above 7%,” DerGurahian said in a note emailed to The Epoch Times.

The price of a gallon of unleaded gasoline is above $5, and diesel is $7.39, at a gas station in Ann Arbor, Mich., on Sept. 20, 2026. Jacob Burg/The Epoch Times
Crude prices have fallen sharply this week, with U.S. oil down about 10 percent to around $91 per barrel. Brent, the international benchmark, returned above $100 midweek.
As of Sept. 22, the national average for a gallon of diesel has risen to $6.52, according to the American Automobile Association.
Meanwhile, the next major inflation report will be August’s personal consumption expenditures (PCE) price index, the Fed’s go-to inflation measure.
After that, the September consumer price index report will be released in mid-October.
The Cleveland Fed projects annual headline consumer inflation will jump to 3.5 percent, but core inflation, which strips out volatile energy and food prices, will hold steady at 2.4 percent.
Until then, investors are leaning toward another quarter-point rate hike at the October Federal Open Market Committee policy meeting after the Fed followed through last week on the first increase to the benchmark federal funds rate since July 2023.
“Those expectations are not set in stone though,” DerGurahian said.
“If oil prices move lower or the September core inflation reading comes in softer than expected, the October hike could be pushed further out. Continued improvement could even cause markets to remove one of the three future hikes currently priced in.”
Fed Chairman Kevin Warsh will hold the next two-day meeting on Oct. 27 and 28.
US Business Is ‘Clearly Booming,’ Says S&P Global’s Chief Economist
U.S. business conditions strengthened to their best level in five years this...
Judge Dismisses Michigan Case Accusing Oil Majors of Suppressing Renewables
A federal judge dismissed an antitrust lawsuit in which Michigan accused four...
Trump Says Iran Is Open to Ending the War
President Donald Trump in the Oval Office of the White House in...
Rubio to Meet Lavrov in New York Amid Trump’s Russia–Ukraine Peace Push
U.S. Secretary of State Marco Rubio will meet Russian Foreign Minister Sergei...