US Private Credit Default Rate Hits Record High in August: Fitch
 Andrew MoranUpdated 3 hours Ago3 Mins read
Stress in the U.S. private credit market persisted last month as the default rate reached an all-time high, Fitch Ratings said in a new report on Sept. 14.
The industry’s challenges had spooked Wall Street earlier this year, but faded into the background as investors wrestled with the war in Iran and renewed inflation fears.
But private credit woes linger, with August’s default rate rising to a record 6.3 percent, from 6.1 percent in July, the credit rating agency reported.
Watching about 1,500 private credit issuers, Fitch registered 14 default events, the highest monthly total in the trailing 12 months ending in August 2026. It identified three serial defaulters—issuers that have defaulted multiple times—and 11 unique defaulters.
Multiple default events were centered in healthcare, general business services, and transportation and distribution. The rest were spread across eight other industries.
Despite private credit’s issues stemming from volatility occurring in software this past winter, the sector maintained the lowest default rate among the largest industries, less than 1 percent.
This follows a report by global investment bank Houlihan Lokey that the smallest private credit borrowers—those with less than $100 million—are also facing difficulty.
For borrowers with less than $20 million in EBITDA—also known as earnings before interest, taxes, depreciation, and amortization—the default rate was almost 4 percent by borrower count, according to Houlihan Lokey’s Private Credit DataBank.
Additionally, 12 percent of loans now trade below 90 cents on the dollar, up from around 1 percent in 2023.
Although Apollo Global Management, Blackstone, and KKR have captured Wall Street’s attention, default risks are concentrated among the smaller cohort, says Cindy Ma, managing director at Houlihan Lokey.
“The increase is concentrated, not broad,” Ma said in a Sept. 10 news release. “When one weights the full market by loan size, defaults remain below 1 percent because the largest borrowers continue to perform. We expect this divide by borrower size to define the market through the balance of the year.”
But the fundamentals are improving, with median revenues growing almost 7 percent and median EBITDA climbing more than 7 percent.
“Leverage remained in line with historical levels, pointing to sustained underwriting discipline among issuers,” the report stated.
The biggest private credit names remain under close watch.

Signage for Blackstone is seen outside the 345 Park Avenue building in Midtown Manhattan in New York on July 29, 2025. Timothy A Clary/AFP via Getty Images
Blackstone said in a Sept. 11 regulatory filing that it continues to cap withdrawals from its $77.2 billion flagship credit fund. The company said investors sought to withdraw about 10 percent of shares in the third quarter, similar to the previous quarter’s number.
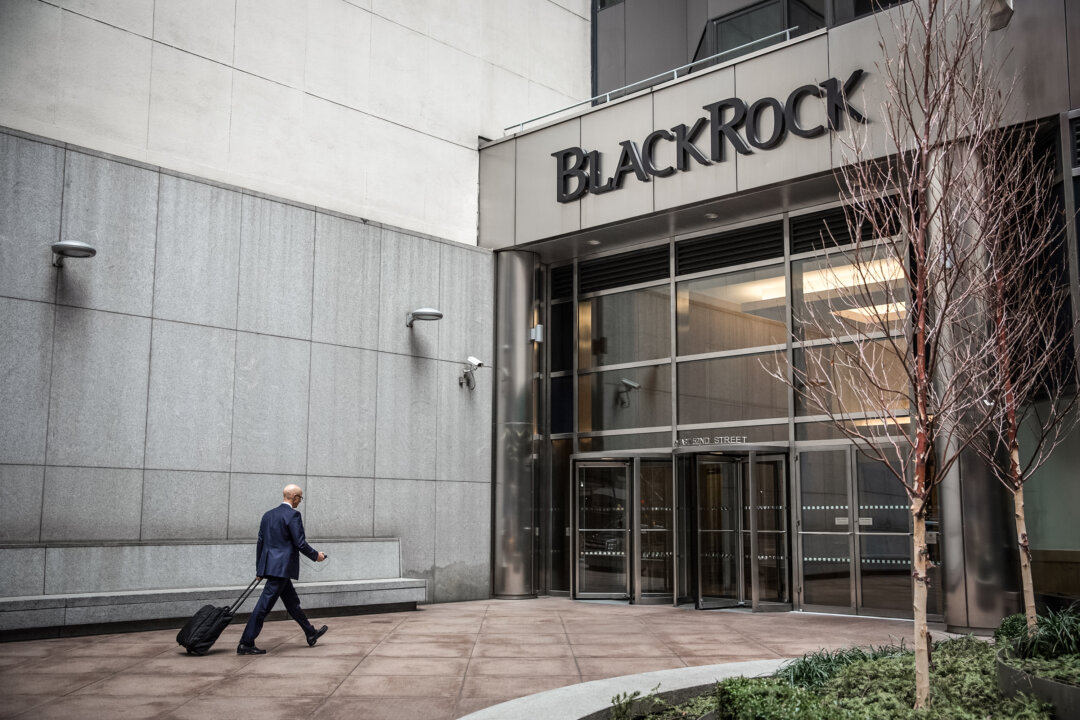
Asset manager BlackRock, meanwhile, reported that private credit fund redemption requests slowed in the third quarter.
Looking ahead, conditions are likely to improve, says Natalia Lojevsky, managing director at CIFC Asset Management.
“Private credit has faced concentration issues and negative headlines, but from our perspective, the issues that have been reported are really concentrated in one part of the market,” Lojevsky said in a note emailed to The Epoch Times.
In the lower middle market, however, investments are broader and tied to the more conventional economic landscape rather than artificial intelligence and tech hyperscalers, “providing differentiated exposure.”
Monitoring the Fed
The Federal Reserve’s September policy meeting has become one of the month’s most anticipated events for Wall Street and Main Street.
Economists and investors overwhelmingly expect the Fed to raise interest rates by a quarter point—the first since July 2023—lifting its benchmark federal funds rate to a new target range of 3.75 percent to 4 percent.
But while this decision could filter through the broader economy, it could be consequential for the private credit sector.
Private credit is highly sensitive to the economic environment, primarily due to elevated leverage and debt levels. Plus, the industry’s portfolios are generally structured as floating-rate, meaning interest rates move up or down based on benchmarks such as the federal funds rate.
Interest rates have already been accelerating over the last several weeks as investors price in tighter monetary policy on persistent war-driven inflation concerns.
The benchmark 10-year Treasury bond yield briefly topped 5 percent to kick off the trading week for the first time in more than three years.
Reuters contributed to this report.
Senate to Hold Key Vote on Major Crypto Bill
The Senate will hold a procedural vote on a sweeping cryptocurrency bill...
Federal Reserve Opens Highly Anticipated September Meeting
The Federal Reserve is opening its closely watched two‑day policy meeting on...
US Will Not Ban Oil Exports, Interior Secretary Says at G20 Energy Meeting
U.S. Interior Secretary Doug Burgum told reporters on Monday that the United...
Diesel Hits New High of $6.23 as Trump Urges Ukraine to Halt Russian Refinery Attacks
The national average price of diesel climbed to a fresh record of...